How to Choose the Right Basis of Accounting for Nonprofits

what is accrual accounting method for churches

Whether the reasons for non-profits favoring the cash method are based in fact or in fallacy, it is important to consider what is best for the organization. And if you do choose to switch, keep in mind that most organizational software allows for a seamless switch. This means that if your business were to grow, your method of accounting would not need to change. With accrual accounting, you record income and expenses as they are billed and earned.
what is accrual accounting method for churches

Tax Basis

So, if today a donor pledges to donate $100 to you next year, you’ll record that donation today rather than next year when the money will arrive in your bank account. This is the simplest form of accounting, where transactions are recorded when cash changes hands. In addition to federal laws, churches must also comply with state regulations. These may include annual reporting requirements, property tax exemptions, and employment laws.

  • For example, QuickBooks users have the option to perform reports on an accrual basis while running on a cash basis to prepare tax returns.
  • When a for-profit business sells a service, the revenue is added to a single general ledger, which records the company’s financial transactions and balances.
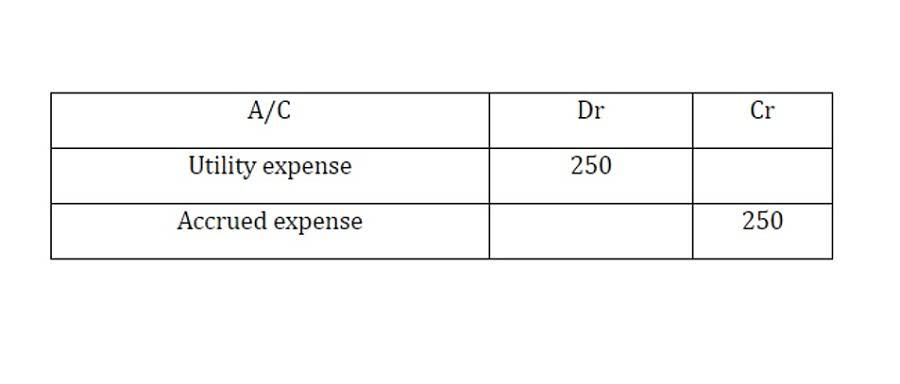
  • Accrued expenses are recorded as accounts payable in a business’s balance sheet.
  • Shoeboxed is an expense & receipt tracking app that helps you get reimbursed quickly, maximize tax deductions, and reduce the hassle of doing accounting.
  • The illustration above shows these events occurring during different periods.

Contribution Statements

  • Under cash basis accounting, transactions are recognized based on the movement of cash.
  • The method you select will determine how you classify, record, and report on your income and expenses.
  • In addition, when cash is tight, cash method accounting is the easiest way to manage bank balances.
  • When choosing software, consider features like user-friendliness, scalability, and integration with other tools like donor management systems.
  • For example, using the accrual method a nonprofit would recognize a pledge as income.

The wise accounting instructor rebutted by explaining contra asset account that we need to understand how to do accounting with a pencil and paper before we understand how to do it using software programs. AICPA author Marc Kotsonas, CPA, Officer- Mahoney Ulbrich Christiansen Russ shared the following six factors in choosing a basis of accounting. Take our 2-minute survey to find out if outsourced accounting and bookkeeping is a good fit for your organization. On the other hand, for-profits sell services or products to maximize profits for the owners. If you need to raise a certain amount of money, you can craft a fundraising plan or hire more staff so you don’t miss the opportunity to do so. All receipts and documents are stored in the cloud, so they are accessible anywhere, which reduces the risk of losing important paperwork.

  • Since these revenue streams come from the congregation and church supporters, they can have restrictions, meaning money must be spent on a specific project or activity the church leader or donor requests.
  • We invite you to learn more by reading our articles on Outcome measures,  improving reporting, and increasing efficiency.
  • Fund accounting requires bookkeepers to create different funds for separate revenue and expenses.
  • It helps to organize and track expenses related to specific programs or events so you can budget and be accountable.
  • Publicly traded companies have a duty to report an accurate view of their financial well-being to shareholders.
  • Donorbox integrates with QuickBooks to help you manage your accounting while raising more for your church!

Cash vs. Accrual Accounting For Non-Profits: Which is Right for Your Organization?

When choosing software, consider features like user-friendliness, scalability, and integration with other tools like donor management bookkeeping and payroll services systems.
what is accrual accounting method for churches

Even if you don’t handle your own financial reporting, it’s accounting for churches vital to know how each one works so you can choose the best bookkeeping practices for your business. Unlike for-profit businesses, churches often manage multiple funds with specific purposes such as building, ministries or mission funds. The chart of accounts allows you to track each fund separately, ensuring transparency and responsible allocation of resources. This is a common approach for smaller nonprofits, as it mirrors a personal “checkbook accounting,” entering debits or credits as they are completed.
what is accrual accounting method for churches

This is due to the timing gap between the sale/purchase and the receipt/payment of cash. Under the accrual basis of accounting, revenue is recognized when earned and expenses are recognized when incurred, regardless of whether payment has been received or disbursed. This method follows the matching principle of accounting, where revenue and expense are captured in the period they were generated. Using most nonprofit accounting software the switch can be rather simple, and painless. For example, QuickBooks users have the option to perform reports on an accrual basis while running on a cash basis to prepare tax returns. Click here for information on how to start running nonprofit reports using the accrual method in QuickBooks3.
Understanding Accounts Payable AP With Examples and How to Record AP

Accounts payable are amounts which are owed by a the direct write off method business to its suppliers for the purchase of trade goods or services, they are sometimes referred to as trade payables or trade creditors. Under normal circumstances, they are normally unsecured, and non-interest bearing. It is clear that buyers with sufficient cash balances or a readily available line of credit should take advantage of the early payment discounts.

How to Record Payments in Accounting?

Monitoring key performance indicators (KPIs) helps optimize workflows and improve vendor relationships. To maximize the benefits of early payment discounts, businesses need to manage their cash flow effectively and prioritize payments. This requires careful planning and a good understanding of the company’s financial position. Taking advantage of early payment discounts can improve the bottom line and strengthen supplier relationships. Effective management of invoice credit terms is a key aspect of the accounts payable process, impacting the overall financial health of the business. These credit terms have significant implications for cash flow and payment schedules.

  • Proper recording of A/P is crucial so that you don’t miss payments and incur late payment fees.
  • Accounts payable can be considered a credit or a debit, depending on the transaction involved.
  • In most cases, bills payable is a direct reference to accounts payable, with the two terms used interchangeably.
  • For instance, 2/10 net 30 is the trade credit that your suppliers offer for the sale of goods or services, meaning you’ll receive a discount of 2% if you pay the amount due within 10 days.
  • Accounts payable, also known as AP, is a general ledger account sitting in the current liabilities section of your company’s balance sheet.
  • At the end of every accounting period (year, quarter, month, 5-week period, etc.) it is important that the accounts payable processing be up-to-date.
  • The amount in the Insurance Expense account should report the amount of insurance expense expiring during the period indicated in the heading of the income statement.

When the payment is made to a creditor or supplier:

The process starts professional bookkeeping online bookkeeping services with tracking expenditures and ensuring timely payments to vendors, which helps maintain good supplier relationships and prevent disruptions in the supply chain. While the business owes the supplier the money, the outstanding amount is classified as an accounts payable in the accounting records of the business. The accounting method under which revenues are recognized on the income statement when they are earned (rather than when the cash is received). When confirming accounts payable, your company’s auditors must take a sample of accounts payable. Further, special emphasis must be given to accounts payable representing larger transactions. Once the sample invoices are reviewed, each of them must be confirmed and verified.

Trade payables constitute the money a company owes its vendors for inventory-related goods, such as business supplies or materials that are part of the inventory. The $500 debit to office supply expense flows through to the income statement at this point, so the company has recorded the purchase transaction even though cash has not been paid out. This is in line with accrual accounting, where expenses are recognized when incurred rather than when cash changes hands. Proper double-entry bookkeeping requires that there must always be an offsetting debit and credit for all entries made into the general ledger. To record accounts payable, the accountant credits accounts payable when the bill or invoice is received. Accounts payable (AP), or “payables,” refers to a company’s short-term obligations owed to its creditors or suppliers, which have not yet been paid.

Properly record accounts payable is crucial for maintaining accurate financial statements. This process requires both a debit and a credit entry in the company’s accounting system. When an invoice for goods or services purchased on credit is recorded, the corresponding expense or asset account is debited, and the accounts payable account is credited. In general ledger an account titled as “accounts payable account” is maintained to keep record of increases and decrease in accounts payable liability during a period. Accounts payable account is credited when something is purchased on credit and debited when a payment is made to a creditor or supplier for a previous credit purchase (see rules of debit and credit). When the balance how to reconcile supplier invoices sheet is drawn, the balance shown by this account is reported as current liability.

  • Recording payments in accounting can otherwise be referred to as “accounts payable,” which means the total amount a given company owes to companies or suppliers for products or services.
  • Under the accrual method of accounting, the company receiving goods or services on credit must report the liability no later than the date they were received.
  • Certain purchases of goods and/or services may be subject to state sales taxes.
  • They are sealed in envelopes, labeled with the appropriate addresses, and sent to the intended recipients.
  • A current liability is defined as an amount due to creditors within 12 months.
  • This is why companies set up short-term notes payable (such as a revolving line of credit with the bank).

Is Accounts Payable a Debit or Credit? Understanding AP in Accounting

However, if you have a large number of accounts payable, you’ll first record the individual accounts payable in a sub-ledger. You can also include the payment terms agreed upon by the suppliers, which will specify the time period that you will take to make payment to your suppliers. When you’re starting your business, you’ll need to add the details of all your suppliers into your accounting software or Microsoft Excel Sheet. The chart of accounts helps you track your accounts payable expenses in a proper manner, and you can also generate your chart of accounts in Microsoft Excel or Google Sheets. Liabilities, equity, and revenue increase with credits and decrease with debits.

Financial Accounting

Once it reaches the hands of the correct person, the details of the invoice are then inputted into a file such as a spreadsheet or an accounting system, which is saved. You may now be wondering how the subsidiary ledger for Accounts Payable and the General Ledger are recorded? You’ll also need to include certain clauses in the supplier contract relating to penalizing suppliers, this is in case of non-performance or underperformance. Talk to bookkeeping experts for tailored advice and services that fit your small business. If Sam had not received the above invoice until June 2, he would have to accrue the expense for May, since that’s when the expense occurred.

Understanding how these apply to accounts payable is essential for accurate bookkeeping and creating financial statements. Each transaction impacts debits and credits differently, depending on whether the transaction involves an increase or decrease in assets, liabilities, or equity. Vendor invoices are requests for payment from suppliers for goods or services received on credit. The accounts payable process involves receiving and processing these invoices, ensuring they are accurate and legitimate.

Company

AP is a current liability, as it’s a short-term debt, ranging from days to a year. Understanding the below-given scenarios helps businesses manage their accounts payable effectively, balancing supplier relationships with cash flow needs. This transaction reflects the debt payment, decreasing accounts payable through debit and reducing cash through credit, as cash leaves the company to settle the obligation.

How to Record Payments in Accounting The Accounts Payable Process

These companies record their purchase transactions in general journal, along with other transactions. Bills payable, like accounts payable, are always recorded as a credit on your balance sheet, with the balance posted as a debit when paid. However, when you pay an how is petty cash reported in financial statements invoice, the accounts payable account is debited, resulting in a reduced accounts payable balance. Accounts payable represent money owed to vendors and suppliers, making it a current liability account.

The Effect of Accounts Payable on Financial Statements

Prompt payment reconciliation is crucial for detecting and preventing fraud in accounts payable. Compared to two-way matching, which only verifies the invoice against the purchase order, three-way matching is more comprehensive. It involves key stakeholders from purchasing, receiving, finance, and the vendor, making it a thorough verification process that enhances the accuracy of financial records.

  • Bills payable refer to the invoices you receive from your suppliers and vendors requesting payment.
  • Also, he pays suppliers by scheduling pay checks and ensures that payment is received for outstanding credit.
  • Since Accounts Payable is a liability account, it should have a credit balance.
  • In both accounts payable (AP) and accounts receivable (AR), you will see credits and debits used when the value in your account increases or decreases.
  • Vendors often send statements to their customers to indicate the amounts (listed by invoice number) that remain unpaid.

Ask Any Financial Question

The transaction would be recorded in your general ledger as a credit to accounts payable, and a debit to the inventory account (an asset account). A trial balance is a worksheet where all the ledgers are compiled into debit and credit column totals. Then, once you’ve made a payment to the vendor, you would credit the cash account (credit decreases an asset account), and debit your AP account (debt will decrease a liability account).

When you’re using accrual accounting every transaction should have a debit entry and a credit entry. By analyzing payment terms and optimizing the timing of payments, companies differences between cash and accrual accounting can improve their financial standing while also strengthening their negotiating power with suppliers. Accounts payable are a liability account that records the amount of money you owe to other parties. Bills payable refer to the invoices you receive from your suppliers and vendors requesting payment.

Assets

Liability accounts detail what your company owes to third parties, such as credit card companies, suppliers, or lenders. For example, let’s say you need to buy a new projector for your conference room. Since money is leaving your business, you would enter a credit into your cash account. You would also enter a debit into your equipment account because you’re adding a new projector as an asset. After the invoice is verified for accuracy, three-way matching is complete, and the invoice is approved, it will need to be entered into the general ledger or your accounting software application. When those invoices are paid, the transaction is posted on the left side of the general ledger as a debit, reducing the account balance.

Accounts Payable Debit Or Credit

On the other hand, if your business is considered as taking advantage of discounts on early payments if it is paying its suppliers quickly. For example, the ‘Accounts Payable Aging Summary’ report, not only tells you about the vendors that you owe money to, but it also highlights the invoices against which payments are overdue. Streamlining the accounts payable process is an essential part of growing and harry vance – author at simple-accounting.org developing your business, though, as managing accounts payable is a backend task, it is often overlooked. You need to make your accounts payable process efficient so that it provides a competitive advantage to your business. Credits boost your revenue accounts since they represent income your business has earned. For example, when a customer makes a purchase, you credit your revenue account, which increases your total income.

  • It is also necessary to review the receiving reports that have not yet been matched to vendor invoices.
  • However, in certain situations, the title to goods passes to the buyer before the physical delivery is taken by him.
  • Invoice credit terms define when a payment is due and any potential discounts for early payment.
  • This entry increases inventory (an asset account), and increases accounts payable (a liability account).
  • Negotiating favorable credit terms with suppliers can improve cash flow and reduce costs of goods and services.
  • Accounts payable represent money owed to vendors and suppliers, making it a current liability account.
  • You’ll need to ensure that a centralized invoice processing system is in place.

All accounting transactions are noted in the general ledger as a journal entry. The transactions are noted as debit, i.e., money going out of the company, or credit, i.e., money coming into the company. An increase in accounts payable could indicate that a company is managing its cash flow strategically, although excessive liabilities may raise concerns about financial stability. For instance, when a company purchases inventory on credit, it not only increases its assets but also its obligations, highlighting the interconnectedness of financial elements in accounting. In addition to these operational benefits, accounts payable is also crucial for compliance and auditing purposes. Accurate records of accounts payable transactions are essential for financial reporting and ensuring that a company adheres to accounting standards.

In summary, understanding accounts payable as a liability is crucial for not only maintaining accurate books but also managing the broader financial health of an organization. By mastering the complexities of debits and credits, it becomes easier to navigate the intricacies of accounting and finance. This process ensures fidelity and accuracy in recording liabilities and prevents discrepancies that could lead to financial mismanagement.

This tech can also prevent your company from costly mistakes and help better track data for accurate audit reporting. This duality ensures accurate financial records and compliance with the double-entry accounting system, where every transaction is represented equally through debits and credits. Essentially, accounts payable allows companies to manage cash flow more effectively while ensuring they have the resources necessary to operate and grow. It is not just a mere accounting entry; it reflects the operational efficiency of a business and its ability to negotiate favorable terms with suppliers, which can significantly impact profitability. It signifies an increase in liabilities, equity, or revenue or a decrease in assets or expenses.

Debit totals are always on the left side of your accounting journal, while credit entries are on the right side of the journal. Accounts payable indicates purchases made on credit owed to the creditor at a later date. Accounts receivable are goods supplied to a customer on credit, owed at a later date. This article delves into the nature of accounts payable, its importance, and how it fits within the broader context of accounting principles. Credit your AP account with the amount, and debit the corresponding asset account (like inventory or equipment, depending what you’ve purchased).

When looking at basic examples of accounts payable, you will often be referencing a purchase or vendor invoice. After the seller communicates this to you and the invoice is accepted, you will debit your purchases or inventory account with the value of the items, then credit your AP account with that same amount. When this is a short-term debt, you will later debit balance your AP account when you pay back the obligation.

Dividends in Accounting

the dividends account is:

For a dividend to be paid, the corporation’s board of directors must formally approve/declare the dividend. Hence, the board of directors may decide that a dividend will not be declared. Dividends represent the reward that a company pays to its shareholders in exchange for their investment. Companies need to distribute dividends for various reasons which may include satisfying shareholder needs or maintaining a positive market perception. There are three different types of dividend policies that companies can adopt, including constant, residual, and stable dividend policies.

Financial Accounting

Dividends can be accounted for using either accrual or cash flow methods depending on the company’s financial activity during a specific period. The accrual method considers regular payments made by the company (regardless of whether shareholders have received them or not). In contrast, cash flow accounting only considers actual dividend payments received by shareholders during the period under analysis. When a company pays a dividend to its shareholders, it’s considered a distribution. The distribution is recorded on the company’s balance sheet, affecting the operating cash flow statement.

the dividends account is:

Invest $18,000 in These 2 Dividend Stocks for $5,742.24 in Passive Income

In some jurisdictions, tax credits or deductions are available to mitigate the impact of double taxation. For example, in Canada, the dividend tax credit allows individuals to reduce their tax liability on dividends received from Canadian corporations. This credit is designed to account for the corporate taxes already paid on the distributed profits, thereby reducing the overall tax burden on shareholders. Such mechanisms can significantly influence investor behavior and the attractiveness of dividend-paying stocks. Dividends can take various forms, each with distinct accounting treatments. Understanding these differences is crucial for accurate financial reporting and analysis.

the dividends account is:

What’s significant for the investment strategy for accounting for dividends?

the dividends account is:

If a company’s board of directors decides to issue an annual 5% dividend per share, and the company’s shares are worth $100, the dividend is $5. Economists Merton Miller and Franco Modigliani argued that a company’s dividend policy is irrelevant and has no effect on its stock price or its cost of capital. Funds may also issue regular dividend payments as stated in their investment objectives. Dividends are the percentage of a company’s earnings that is paid to its shareholders as their share of the profits. Dividends are generally paid quarterly, with the amount decided by the board of directors based on the company’s most recent earnings. If it doesn’t have the necessary cash to pay a dividend, it must borrow money or sell off assets.

the dividends account is:

This approach can be advantageous for both the company and the shareholders. For shareholders, DRIPs provide a convenient way to increase their investment Partnership Accounting without incurring brokerage fees, and they benefit from the compounding effect of reinvesting dividends. Over time, this can lead to significant growth in their holdings, especially if the company performs well.

  • Economists Merton Miller and Franco Modigliani argued that a company’s dividend policy is irrelevant and has no effect on its stock price or its cost of capital.
  • This is essentially a cutoff date for assigning the dividend payment when shares change hands.
  • The amount of money needed to pay a dividend is called the required payout ratio.
  • For cash dividends, the company debits the “Dividends Payable” account and credits the “Cash” account.
  • The IRS also receives a copy of each 1099-DIV to track a person’s taxable investment income.
  • The final entry required to record issuing a cash dividend is to document the entry on the date the company pays out the cash dividend.

Cash dividends offer a way for companies to return capital to shareholders. A cash dividend primarily impacts the cash and shareholder equity accounts. There is no separate balance dividend account sheet account for dividends after they are paid.

The 1 Canadian Stock I’d Buy and Hold Forever in a TFSA

As you would expect, dividends shouldn’t impact the operating activities of your company. That means declaring, paying, and recording dividends won’t change anything on income summary your income statement or profit and loss statement. Most of the time, businesses and business owners aren’t required to issue dividends. If the company has paid the dividend by the end of the fiscal year, then there will be no dividend payable liability listed on the balance sheet. As the business does not have to pay a dividend, there is no liability until there is a dividend declared. As soon as the dividend has been declared, the liability needs to be recorded in the books of account as a dividend payable.

Accounting for Nonprofits Tax Form 990 CPA Firm CA

bookkeeping for nonprofits Fresno

A generous car dealership gives you Airbnb Accounting and Bookkeeping a vehicle for free, but that doesn’t mean it wasn’t a transaction! You’ll need to record the car as an in-kind donation from the dealership, noting even details about the model and make of the vehicle. The donations should be recorded on the statement of activities. The entry should contain information such as the donor’s name, the amount of money, and the date. Fortunately, nonprofit professionals don’t have to worry about your financial information if you choose FreshBooks.

bookkeeping for nonprofits Fresno

Hotel CPA Services

bookkeeping for nonprofits Fresno

Trust in Jitasa to navigate the complexities of nonprofit financial management in Fresno, ensuring your mission flourishes in this vibrant and evolving city, contributing to a healthier, more inclusive community. We are fully capable of assisting a range of non-profits including religious organizations, art centers, social welfare organizations, recreational clubs, business leagues, schools, and an array of charities. Our goal is to help them manage their bookkeeping and accounting needs so that they can do what they were established to do – help their local communities.

Voted “Top U.S. Firm” 3x for a reason…

  • For example, bookkeeping ensures your nonprofit uses its revenue wisely and maintains its tax-exempt status.
  • Jitasa’s tax specialists have filed more than 4,000 tax returns for nonprofits of all shapes and sizes.
  • Over 40,000 nonprofits and churches trust Aplos Accounting tools to help them succeed in their missions.
  • Essentially, you should view bookkeeping as the financial oversight process that’s necessary for operating your nonprofit daily.
  • For example, let’s say your nonprofit needs a car to run errands for the organization.
  • Aplos’ integrated suite makes critical management tasks straightforward and uncomplicated.

I can help you set up and maintain your non-profit organization’s tax-exempt status by handling all the IRS reporting for you. Jitasa’s tax specialists have filed more than 4,000 tax returns QuickBooks for nonprofits of all shapes and sizes. In addition to your IRS Form 990, we’ll prepare any other forms you may need. Get it right, and you’ll spend less time wrestling with numbers and more time changing the world. Aplos has everything you need in one place for streamlined nonprofit and church management. For example, let’s say your nonprofit needs a car to run errands for the organization.

  • Aplos is a robust accounting system that allows you to keep track of your grants, programs, and fundraising so you can give your board clarity on your finances.
  • Using the details you recorded about your nonprofit’s transactions, create a broad overview of your financial position and develop a plan to get your revenue where it’s supposed to be.
  • You have to know the area to plan a route, and the same can be said about your nonprofit’s budget.
  • These financial statements can provide helpful insight into your nonprofit’s financial health so that you can adjust accordingly and plan your next moves.
  • You should also hire a financial officer or a treasurer who knows how to do bookkeeping for a nonprofit and is familiar with specialized accounting software.
  • We are a small team obsessed with detail, simplicity, and processes.

Statement of Cash Flows (Your Money’s Journey)

As a CPA firm that specializes in working with not-for-profits, we also understand the unique accounting needs and financial challenges faced by these organizations. Think about your budget like a roadmap to where you’ll spend your money. You have to know the area to plan a route, and the same can be said about your nonprofit’s budget. Accurate and timely bookkeeping practices will make the job of those tasked with budgeting much easier to tackle. Think of bookkeeping as studying for a test—it’s the necessary first step you must take to prepare yourself for the big exam.

Why Nonprofit Accounting is Different

bookkeeping for nonprofits Fresno

For organizations tracking fresno bookkeeping budgets and financials for grants, programs, departments, or multiple locations. Aplos is a robust accounting system that allows you to keep track of your grants, programs, and fundraising so you can give your board clarity on your finances. Over 40,000 nonprofits and churches trust Aplos Accounting tools to help them succeed in their missions. No one knows your nonprofit better than you do, which is why you should hire a professional bookkeeper to get your records in order and leave the decision-making up to your organization’s leaders.

bookkeeping for nonprofits Fresno

Prepaid Insurance: Is It an Asset or Owners Liability?

He firmly believes that anyone can build a solid financial foundation as long as they are willing to learn. He runs MoneyNing.com, where he discusses every day money issues to encourage the masses to think about their finances more often. Learn Accounting Easily with our free blog that simplifies accounting, finance, and business concepts for what are trade receivables students, accountants, and small business owners. Some insurers prefer that insured parties pay on a prepaid schedule such as auto or medical insurance. Julia Kagan is a financial/consumer journalist and former senior editor, personal finance, of Investopedia. In this case, assuming that the service represented by the asset expires equally each month, the Prepaid Insurance account must be reduced by $900.

and Reporting

For example, if a company pays $12,000 for a one-year policy, the monthly insurance expense would be $1,000. Each month, the adjusting entry transfers this amount from prepaid insurance to insurance expense. Such adjustments are critical for maintaining accurate financial records and ensuring compliance with accounting standards.

How Inflation Affects Your Bank Account: What You Need to Know

As prepaid insurance is an asset that will expire through the passage of time, the cost of expiration will need to be recognized as an expense during the period. This adjusting entry is necessary for the company to not overstate its total assets as well as to not understate its total expenses during the period. To estimate the amount of a prepaid asset’s monthly benefit, divide the total cost of the asset by the number of months of benefits the asset represents. Prepaid or unexpired expenses can be recorded under two methods – asset method and expense method. On 1 September 2019, Mr. John bought a motor car and got it insured for one year, paying $4,800 as a premium. When he paid this premium, he debited his insurance expenses account with the full amount, i.e., $4,800.

Is Prepaid Insurance an Asset?

As of December 31, the company will report Insurance Expense of $100 and its current asset Prepaid Insurance will report $500. The prepaid amount informs the readers of the December 31 balance sheet that the company will not have to pay $500 in cash for insurance during the next five months. When the its time for those who benefited from a housing boom to pay up full amount is received by the insurer, accounting will treat the payment as an asset. An entry will then be created on the books to move this amount from current assets to the expense side. The leftover ($16,000 in this case) will be counted as prepaid insurance for the insurer.

📆 Date: 15-16 Feb 2025🕛 Time: 8:30-11:30 AM EST📍 Venue: OnlineInstructor: Dheeraj Vaidya, CFA, FRM

Most calculations dealing with prepaid insurance involve determining how much of that prepaid insurance expense is recognized in each accounting period. This is usually done by dividing the total premium paid by the coverage period, which may be expressed in months or years. Prepaid Insurance is the insurance premium paid by a company in an accounting period that didn’t expire in the same accounting period. Therefore, the unexpired portion of this insurance will be shown as an asset on the company’s balance sheet. For instance, the Internal Revenue Service (IRS) allows businesses to deduct insurance expenses only in the period they are incurred.

  • Things change if a business is using the “accrual basis” accounting method.
  • When the company makes an advance payment for insurance, it can make prepaid insurance journal entry by debiting prepaid insurance account and crediting cash account.
  • In this case, assuming that the service represented by the asset expires equally each month, the Prepaid Insurance account must be reduced by $900.
  • Prepaid assets represent the right to receive future services, while deferred revenue represents the right to receive future cash payments.
  • As the coverage term progresses and sections of the prepaid insurance are expensed, the prepaid insurance account is credited to reflect the decrease in the prepaid amount.
  • Prepaid insurance is the portion of an insurance premium that has been paid in advance and has not expired as of the date of a company’s balance sheet.
  • Both the International Financial Reporting Standards (IFRS) and Generally Accepted Accounting Principles (GAAP) guide this classification based on liquidity and time horizon.
  • This unexpired cost is reported in the current asset account Prepaid Insurance.
  • This is because the company has a contractual obligation to pay for the insurance coverage, even though the coverage has not yet been received.
  • As the coverage period runs out, portions of prepaid insurance are expensed, and gradually the prepaid amount decreases to its complete use or expiration date.
  • This often allows more flexibility in recognizing and transitioning prepaid insurance to expenses, requiring judgment-based decisions.
  • However, the premiums may be marginally higher to account for inflation and other operating factors.
  • This classification requires careful assessment of the policy’s terms and the company’s accounting practices to ensure financial statements accurately reflect the timing and consumption of prepaid assets.

Recording prepaid insurance involves recognizing the payment as an asset on the balance sheet. When a company pays for an insurance policy in advance, the entry debits the prepaid insurance account and credits cash or accounts payable, depending on the payment method. This ensures the financial records reflect the asset’s value at the time of payment. From a financial accounting perspective, prepaid insurance how to calculate retained earnings is considered a prepayment. Recorded as a current asset on the balance sheet, it is progressively accounted for on the income statement as expenses, reflecting the utilization of insurance coverage in each accounting period.

How long can prepaid expenses be reported as an asset?

Technically, I could claim the unused portion when I calculate my net worth. Navigating the differences between International Financial Reporting Standards (IFRS) and Generally Accepted Accounting Principles (GAAP) can be challenging, especially regarding prepaid insurance. While both frameworks promote transparency and consistency, subtle differences in their treatment of prepaid expenses can impact financial reporting. This is because the company has a contractual obligation to pay for the insurance coverage, even though the coverage has not yet been received.

How to Calculate an Operating Budget for a Non-Profit Organization? Chron com

how to calculate operating budget nonprofit

Identify opportunities, threats, and emerging trends likely to influence your activities (both internal and external to your organization). Finally, get clear on and name the goals, organizational values, and priorities that you want to have reflected in this year’s budget. Be sure to include all the payments that have gone toward your mission programs—including international payments.

The Importance of a Nonprofit Operating Reserve – FORVIS

The Importance of a Nonprofit Operating Reserve.

Posted: Tue, 18 Jul 2023 07:00:00 GMT [source]

This category may include cell phones, internet, electricity, water, and other utilities for daily operations. If your nonprofit needs TV streaming, how to calculate operating budget nonprofit cable, or satellite service, include that here too. This category includes things like educational materials, workshops, and conferences.

What Are the Basic Elements of a Nonprofit Budget

When determining how to allocate funds, it is important to consider the organization’s overall goals and objectives. For example, if the goal is to increase access to services, then a greater proportion of funds should be allocated to program expenses. Alternatively, if the goal is to increase donor support, then a greater proportion of funds should be allocated to fundraising expenses. This may involve allocating funds to specific activities or programs that are aligned with the organization’s goals, as well as ensuring that there is enough money allocated to cover the organization’s fixed costs.

how to calculate operating budget nonprofit

An effective operating budget ensures that nonprofits allocate their resources wisely, prioritize their activities, and stay on course toward their goals. A common misconception about nonprofit budgeting is that because nonprofits by definition can’t turn a profit, their operating budgets always have to break even. It can help you organize revenue and expenses, track performance, and make data-driven decisions to support your mission and your organization’s financial sustainability. In nonprofit budgets, around 35% of your expense budget should be used for administrative expenses (overhead) and the other 65% for program expenses. Among your annual projected expenses, include fixed expenses like rent and loan repayments as well as variable expenses like marketing and fundraising costs.

Figure out your expenses

For example, if one of the organization’s goals is to increase its funding from grants, then the budget may need to include funds for research on potential grantors and for writing and submitting grant proposals. The “what and why” of having operating reserves are intertwined and fundamental. Sometimes referred to as a rainy-day fund, operating reserves can provide shelter from a storm in the form of financial resilience and flexibility. Your nonprofit finance team also leverages KPIs to define financial success, measure the health of your nonprofit, and manage your financial standing. Also, because certain grants will be restricted to certain program areas (rather than general operating support), organize the budget so that each program area’s cost is easy to eyeball. Then you can advise your grant writers what areas need more (or less) funding so that grant prospecting is more efficient.

  • Get our FREE guide to nonprofit financial reports, featuring illustrations, annotations, and insights to help you better understand your organization’s finances.
  • In fact, healthy nonprofits will do this to help fund 3-6 months of operating reserves.
  • This category includes all the costs of hiring and retaining staff—including salaries, payroll taxes, health insurance, retirement contributions, and other benefits.
  • Articulate the main purpose of your budget and think about a structure that will best support that purpose.
  • Allocating funds and prioritizing spending are both part of accounting services for nonprofits.
  • While no two nonprofits are exactly alike, there are some best practices that all organizations should use when building their annual operating budgets.
  • Award-winning online accounting software designed for small business owners and accountants.

Is Prepaid Insurance an Asset on Financial Statements?

Prepaid insurance for businesses is very valuable in terms of providing financial stability, budgeting accuracy, and risk mitigation. However, to ensure accuracy of financial statements, it is essential that these are recorded in the correct accounting period. By leveraging HighRadius’ Record to Report (R2R) suite organizations can automate prepaid insurance journal entry management, reducing manual errors and enhancing efficiency. These are payments paid in advance for goods or services that will be received in the future. It provides the benefit of obtaining services at a predetermined cost, which aids in budgeting and financial stability. Among these, one particularly important type of prepaid expense is prepaid insurance.

Recording and Adjusting Entries

When a company pays its insurance payments in advance, it makes a debit entry to its prepaid insurance asset account. As the coverage term progresses and sections of the prepaid insurance are expensed, the prepaid insurance account is credited to reflect the decrease in the prepaid amount. Things change if a business is using the “accrual basis” accounting method. These companies, usually larger corporations, will need to count prepaid expenses (like insurance) as an asset until it’s used up. If the delivery company in our example is using the accrual basis accounting method, then it’ll treat the prepaid insurance that hasn’t been used as an asset on its balance sheet until that amount is used up. A company spending six or seven figures a year on insurance costs will want to count that cash as an asset until it’s actually used.

What is your current financial priority?

  • This is usually done by dividing the total premium paid by the coverage period, which may be expressed in months or years.
  • Businesses can further simplify their accounting processes with AI/ML-powered Transaction Matching automating data extraction and reconciliation enabling firms to experience an auto match rate of 90%.
  • Among these, one particularly important type of prepaid expense is prepaid insurance.
  • Likewise, the net effect of the prepaid insurance journal entry in this example is zero on the balance sheet.
  • If the prepayment covers a longer period, then classify the portion of the prepaid insurance that will not be charged to expense within one year as a long-term asset.

Although Mr. John’s trial balance does not disclose it, there is a current asset of $3,200 on 31 2021 tax return preparation and deduction checklist in 2022 December 2019. This blog covers the ins and outs of prepaid insurance, its importance, advantages, examples, ways of recording, calculations, and much more. For the past 52 years, Harold Averkamp (CPA, MBA) hasworked as an accounting supervisor, manager, consultant, university instructor, and innovator in teaching accounting online. For the past 52 years, Harold Averkamp (CPA, MBA) has worked as an accounting supervisor, manager, consultant, university instructor, and innovator in teaching accounting online. Note that $1,000 is calculated by dividing the total prepaid amount ($12,000) by the number of months in the period (12).

Our Services

  • For instance, many auto insurance companies operate under prepaid schedules, so insured parties pay their full premiums for a 12-month period before the coverage actually starts.
  • When it comes to financial reporting, the classification of prepaid insurance can be a subject of debate.
  • XYZ company needs to pay its employee liability insurance for the fiscal year ending December 31, 2018, which amounted to $10,000.
  • This method guarantees that expenses are accurately allocated during the prepaid period, reflecting the steady utilization of insurance coverage.
  • This is because the company has paid for a benefit that it has not yet received.
  • Prepaid expenses are payments made in advance for goods or services that will be received or used in the future.

This method makes sure that the expenses match the revenues related to them, following the matching principle in accounting. At the payment date of prepaid insurance, the net effect is zero on the balance sheet; and there is nothing to record in the income statement. However, after adjusting entry at the end of the period for the insurance expense, the asset account will decrease while 3.5 process costing the expense account will increase. Likewise, the adjusting entry at the end of the period is necessary for the company to recognize the cost that expires through the passage of time. Calculating the adjustment amount requires understanding the policy’s terms.

This means the company should record the insurance expense at the period end adjusting entry when a portion of prepaid insurance has expired. Accountants must track the consumption of insurance coverage by understanding policy terms such as coverage duration and renewal dates. This systematic allocation of the prepaid insurance asset to the expense account often involves using accounting software to automate tracking and adjustments, reducing errors and enhancing accuracy.

What is the approximate value of your cash savings and other investments?

In this tutorial, we’ll explore the difference between operating leases and finance leases, with a particular focus on the journal entries involved in both. The matching principle is the basis for allocating expenses to the periods in which they are used or consumed. It requires that expenses be matched with the revenues they help generate. Someone on our team will connect you with a financial professional in our network holding the correct designation and expertise.

At the end of each month, an adjusting entry of $400 will be recorded to debit Insurance Expense and credit Prepaid Insurance. The second journal entry shows how 1/12th of this amount is charged to expense in the first month of the coverage period. This adjusting entry will be repeated at the end of each subsequent month to recognize the insurance expense gradually over the year. Suppose that Smith Company, which has a yearly accounting period ending on 31 December, purchases a two-year comprehensive insurance policy for $2,400 on 1 April 2019. In this case, Prepaid Insurance is classified as current assets on the Balance Sheet, as shown below. It refers to the portion of the outstanding insurance premium paid by the company in advance and is currently not due.

What is Prepaid Insurance: Benefits and Examples

Let’s say a delivery company takes out some commercial auto insurance for its fleet of cars. However, it not until month six that the company has used all of the $24,000 worth of insurance. Prepaid insurance is exactly what it sounds like – insurance that’s been prepaid.

Take self-paced courses to master the fundamentals of finance and quality of design and quality of conformance connect with like-minded individuals.

Most calculations dealing with prepaid insurance involve determining how much of that prepaid insurance expense is recognized in each accounting period. This is usually done by dividing the total premium paid by the coverage period, which may be expressed in months or years. Prepaid Insurance is the insurance premium paid by a company in an accounting period that didn’t expire in the same accounting period. Therefore, the unexpired portion of this insurance will be shown as an asset on the company’s balance sheet. For instance, the Internal Revenue Service (IRS) allows businesses to deduct insurance expenses only in the period they are incurred.

Introduction to bookkeeping and accounting: Introduction Open University

fundamentals of bookkeeping

Such integration saves time, cuts costs, and enhances user experience. Apart from providing LLC formation and compliance, EasyFiling is also a reputable financial service firm that helps business owners of all scales with easy bookkeeping. Here are some of the features EasyFiling has that can help streamline your bookkeeping tasks. These are expenses that help to reduce your taxable income, and having proper records of them will save you a good amount in taxes. Deductible expenses include; business trips, meals, equipment bookkeeping purchased, and office space. If properly tracked, you will worry less when tax season comes along since you will have more deductions.

  • When you enroll in the course, you get access to all of the courses in the Certificate, and you earn a certificate when you complete the work.
  • It provides a comprehensive understanding of accounting principles, procedures, and their practical application.
  • Instead of recording income and expenses as they clear your bank, you record them as the income is earned and the expenses are billed.
  • Explore our services to see how we can support your bookkeeping journey.
  • One of the first decisions you have to make when setting up your bookkeeping system is whether or not to use a cash or accrual accounting system.
  • There are different types of cash flow, including operational, investment and financing.
  • The equity accounts include all the claims the owners have against the company.

Depreciation & Disposal of Non-Current Assets

Think of it as having a map that shows exactly where you are and where you need to go. Management Accounting Concepts and Techniques, covers topics such as cost analysis, budgeting, product costing, and performance measures. Highlights the distinction between financial accounting and management accounting, emphasizing the latter’s role in allocating resources within a company. Principles of Strategic Management Accounting, is a book introducing strategic management accounting tools such as budgets, activity, based costing, and performance measures. It provides an analytic framework rooted in academic research to understand and analyze real businesses, emphasizes the role of management accounting tools in managing core in…

  • Data analysis and reports are integral to the decision-making process whether it’s budgeting, planning investments, or increasing the scale of operations.
  • Generating monthly reports helps you monitor your financial health and make informed decisions.
  • It provides the financial clarity needed to make informed decisions and ensures that all financial activities are accurately recorded.
  • These are expenses that help to reduce your taxable income, and having proper records of them will save you a good amount in taxes.
  • Businesses that have more complex financial transactions usually choose to use the double-entry accounting process.
  • At EasyFiling, we can assist you with bookkeeping, starting with daily transactions, and ending with business financial report generation, all customized to however your business needs it.

Liabilities

fundamentals of bookkeeping

Bookkeeping gives you access to detailed financial reports like balance sheets, income statements, and cash flow statements. Bookkeeping is the process of systematically recording, organizing, and maintaining a business’s financial transactions. Think of it as the backbone of your financial health, ensuring that every dollar is tracked and accounted for. With the cash basis of accounting, income is recorded when it’s received, and expenses are recorded as they’re paid. The cash method does not take into account any accounts receivable or accounts payable.

fundamentals of bookkeeping

#9 Basics of Accounting

fundamentals of bookkeeping

At EasyFiling, we utilize sophisticated bookkeeping tools and software that help us and you eliminate manual errors and ensure efficiency. The cloud-based nature of our bookkeeping services gives clients access to their financial records whenever and wherever ensuring that your data is safe while also aiding in collaboration. At EasyFiling, we can assist you with accounting basics bookkeeping, starting with daily transactions, and ending with business financial report generation, all customized to however your business needs it. When tax or audit season arrives, we ensure that every expense has been recorded in your books so that you are prepared for them.

fundamentals of bookkeeping

fundamentals of bookkeeping

The chart of accounts may change over time as the business grows and changes. A small business owner’s day-to-day activities Grocery Store Accounting usually involve managing their business and carrying out the role of a book-keeper. As a book-keeper, the owner’s role would involve the following tasks. Profit Leap empowers businesses with AI-driven financial solutions, real-time insights, and seamless dashboards. We simplify decision-making, boost profitability, and drive growth with cutting-edge tools and expert guidance.

  • Effective bookkeeping will help every owner, whether you are just starting or you are managing an established business, comply with taxes and facilitate transparency.
  • This ensures your financial records are accurate and up-to-date.
  • The general ledger is a master document that categorizes all transactions into different accounts, such as assets, liabilities, equity, income, and expenses.
  • The single and double-entry bookkeeping methods are the ones most commonly used within small businesses.
  • Fundamentals of Accounting, is a document that covers various aspects of accounting, including financial accounting, cost accounting, and management accounting.

Accounting Books for Free!

If you use cash accounting, you record your transaction when cash changes hands. After Barbara completes the book-keeping, Jack takes the records and puts them to use. He transforms the records Barbara has collected in a way that can be used for decision making. He creates financial statements which can be used to see where the business is spending its money, where it is making money, and the financial health of the burger bar.

Recording vs. Analyzing

Introduction to Bookkeeping, is a comprehensive guide that covers the fundamentals of bookkeeping, including accounting principles, types of business organizations, and accounting systems. The course also addresses topics such as depreciation, payroll accounting, petty cash management, and bank reconciliation. Growing businesses that offer credit to customers or request credit from suppliers use the accrual basis of accounting.

Accountant and Bookkeeper Practice Case Studies

bookkeeping and accounting Stories

A consistent bookkeeping routine is essential for staying organized and keeping your finances in check. Think of it like regularly tidying up your home—a little effort each day or week prevents a massive, overwhelming mess later on. This section will guide you in creating a sustainable bookkeeping routine tailored to your startup’s needs. Bookkeepers record financial transactions in ledgers, noting details like dates, amounts, purposes, and bank accounts. In smaller businesses, bookkeepers may handle broader responsibilities, such as processing payroll or assisting with tax preparation. In larger companies, their roles tend to be more specialized, focusing on areas like accounts payable or accounts bookkeeping receivable.

bookkeeping and accounting Stories

Peek inside our private Bookkeeper Launch community to see what students and graduates are saying…

Mingling funds can create a tangled mess, making it difficult to accurately assess your business’s performance and potentially leading to legal and tax issues. Regularly checking your cash flow—the Customers Success Stories money coming in and out—is essential. Understanding your runway (how long your cash will last) and your net profit margin (profit per dollar of revenue) are key metrics.

  • QuickBooks, for example, “is including more AI features in its software that attempt to automatically categorize transactions,” Lagow said.
  • This method recognizes revenue when it’s earned and expenses when they’re incurred, regardless of when cash changes hands.
  • Rekha Mehta, CPA, founder and president of public accounting firm RSMCPA Corp. in Colleyville, Texas, did financial ratios manually years ago.
  • Bookkeeping is the organized recording of all your financial transactions.
  • Startup bookkeeping is the often-overlooked foundation upon which sustainable growth is built.
  • If you’re ready to explore professional accounting support, contact us to discuss your needs.

Listen to: What Does a Bookkeeper Do? Role, Key Duties, and Responsibilities

bookkeeping and accounting Stories

It’s not just about tracking income and expenses; it’s about gaining a clear financial picture to make informed decisions. Certified Bookkeeper This involves managing invoices, creating financial statements, and understanding your cash flow. Choosing the right method from the start can save you headaches down the line. Regularly reviewing your financial statements—at least monthly—is a non-negotiable practice for any startup.

bookkeeping and accounting Stories

Common Bookkeeping Challenges

Susan Landauer, CPA, co-founder and managing partner of Forensic Accounting Services Group LLC, in Albany, N.Y., remembers her first forensic case in 1989, when she looked for fictitious invoices. At that time, she used phone books and called companies directly to see if they existed. Today, Landauer uses the internet and services such as LexisNexis to search for information. “You’re not trucking around to different courthouses to search for information,” she said about her current work. Accounting Today is a leading provider of online business news for the accounting community, offering breaking news, in-depth features, and a host of resources and services.

Company

“If you are somebody who likes to do the busy work, the technology is starting to eliminate that,” Rainey said. Accurate and up-to-date financial reports are more than just compliance requirements; they are powerful tools for guiding your business strategy. They provide the data-driven insights you need to make informed decisions about everything from pricing and product development to marketing and hiring. Finally, the cash flow statement tracks the movement of cash both into and out of your business. It shows where your money is coming from, where it’s going, and how much cash you have on hand.

bookkeeping and accounting Stories